What Business Owners Need to Know
As liability claims continue to increase in size and complexity, many businesses are discovering that their primary insurance limits may not be enough.
That’s where Commercial Umbrella and Excess Liability coverage come into play.
While both provide additional liability protection, they are not the same thing.
COMMERCIAL UMBRELLA
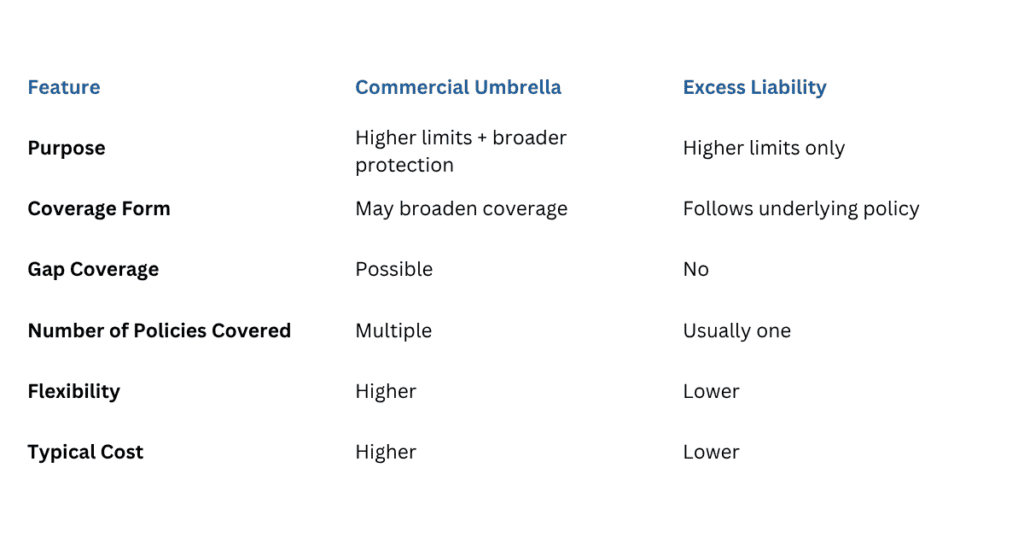
Provides additional liability limits above multiple underlying policies and may broaden coverage.
Key Advantages
· Sits above multiple policies
· May fill certain coverage gaps
· Can provide broader protection than underlying policies
· Often applies to General Liability, Auto Liability, and Employers Liability
Best For
Businesses seeking comprehensive liability protection across multiple exposures.
EXCESS LIABILITY
Provides additional limits above a specific underlying policy.
Key Advantages
· Increases available coverage limits
· Simple, follow-form structure
· Mirrors underlying policy coverage
· Cost-effective way to increase limits
Best For
Businesses that need higher limits for one specific liability exposure.
SIDE-BY-SIDE COMPARISON
HOW IT WORKS
Example Claim
A company vehicle is involved in a serious accident that results in a $3 million lawsuit.
The business carries:
-
$1 million Commercial Auto Liability
-
$1 million General Liability
With Excess Liability
The policy provides additional limits above the Commercial Auto policy once the $1 million limit is exhausted.
With Commercial Umbrella
The policy may provide additional limits and potentially broader protection depending on the policy language.
WHO SHOULD CONSIDER COMMERCIAL UMBRELLA COVERAGE?
Commercial umbrella insurance may make sense for businesses that:
-
Operate company vehicles
-
Own commercial property
-
Work directly with customers
-
Have multiple employees
-
Manufacture products
-
Perform contracting or construction work
-
Face significant liability exposures
KEY TAKEAWAYS
-
Both policies provide protection above primary liability limits.
-
Excess Liability increases limits but generally does not expand coverage.
-
Commercial Umbrella may provide broader protection and coordinate coverage across multiple policies.
-
Understanding the difference can help prevent costly coverage gaps.
-
Coverage varies by carrier and policy form, making regular reviews essential.